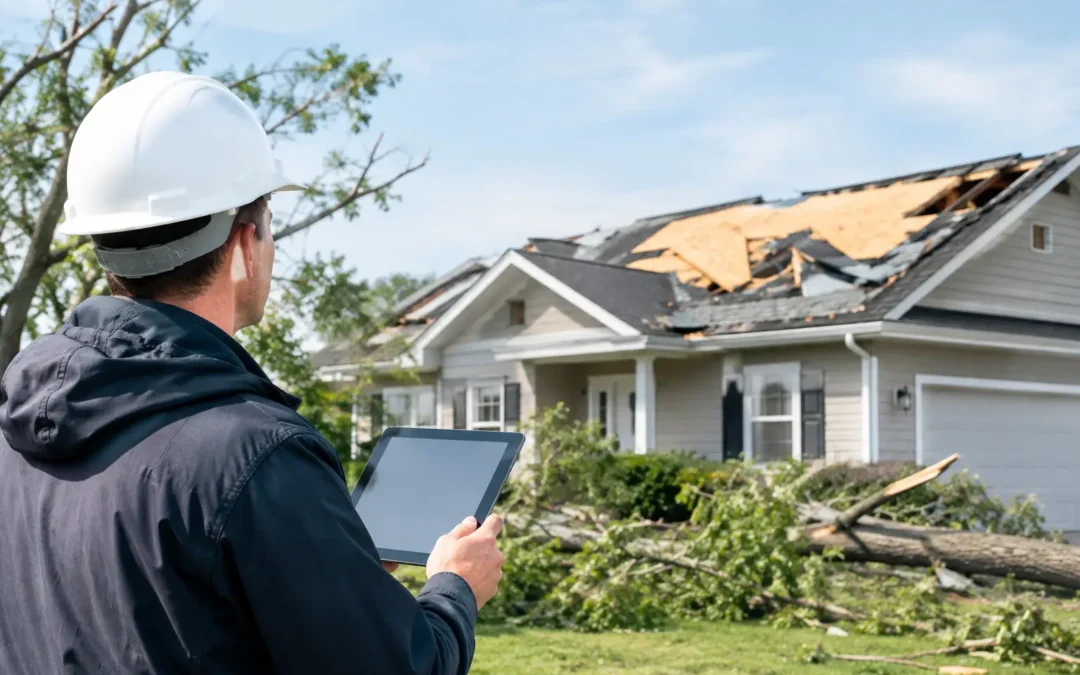
A Hudson Valley storm can leave more than obvious damage behind. A few missing shingles, a bent gutter, or water marks on a ceiling may look manageable at first, but small openings can allow ongoing moisture into the roof deck, attic, walls, and insulation. Effective storm claim restoration starts with protecting the property, documenting what happened, and making decisions before a minor issue becomes a larger repair.
For homeowners, landlords, and commercial property owners, the goal is not simply to file an insurance claim. The goal is to restore the exterior correctly, preserve the evidence your insurer needs, and avoid rushed repairs that create trouble later.
What Storm Claim Restoration Should Include
Storm damage restoration is a coordinated process, not a single repair visit. Depending on the event, it may involve emergency roof protection, a detailed inspection, photographs, a written scope of damage, repairs or replacement, and cleanup after the work is complete.
Wind can lift or crease shingles without blowing them fully off the roof. Hail can bruise shingles and dent metal components. Heavy rain can expose flashing failures around chimneys, vents, skylights, and valleys. Fallen limbs may damage roofing, siding, gutters, fascia, or even structural framing. Winter weather creates its own concerns, including ice dams that push water beneath shingles and into the home.
The visible damage is only one part of the picture. A reliable inspection also looks for moisture intrusion, compromised underlayment, loose flashing, damaged roof decking, blocked drainage, and siding or trim damage that could let water into the building envelope.
Start With Safety and Documentation
After severe weather, avoid climbing onto the roof yourself. Wet shingles, loose materials, and hidden structural damage make roofs dangerous, even for experienced property owners. If there is an active leak, move furniture and valuables away from the area, place a container under dripping water, and take reasonable steps to limit interior damage.
Photograph the property from the ground before anything is moved or repaired. Capture missing shingles, damaged gutters, fallen branches, dented vents, water stains, damaged siding, and debris around the structure. If you have photos from before the storm, keep those available as well. They can help show that the condition changed after a specific weather event.
Save receipts for reasonable emergency expenses, such as temporary water mitigation or protective covering. Do not throw away damaged materials until your insurance carrier advises you to do so. Clear records help establish a timeline and make the claim discussion more straightforward.
Call Your Insurance Carrier Promptly
Report the loss to your insurer as soon as you can, especially when the property is exposed to rain or wind. Ask about your deductible, the claim number, the adjuster process, and any immediate steps the carrier expects you to take to prevent further damage.
An exterior contractor can document storm-related conditions and provide a repair or replacement estimate. However, only the insurance carrier determines coverage, payment, and final claim approval. That distinction matters. A trustworthy contractor should explain the damage clearly and help you prepare for the adjuster visit without promising an outcome they cannot control.
Why Emergency Protection Cannot Wait
A roof that is missing shingles or punctured by debris may need temporary protection before permanent work can begin. Emergency tarping or targeted weatherproofing can help reduce additional rain damage while the claim is being reviewed and materials are scheduled.
This is one area where waiting can become expensive. Insurance policies generally expect property owners to take reasonable steps to prevent further loss. A tarp is not a finished repair, and it should not remain in place longer than necessary, but it can be the right move when the roof is vulnerable and more weather is approaching.
The same principle applies to gutters and siding. A gutter pulled away from the fascia can direct water against the home instead of away from it. Cracked siding, loose trim, or damaged flashing can allow wind-driven rain into places that are difficult to inspect from inside. Fast action protects both the structure and the restoration timeline.
A Thorough Inspection Finds the Damage You Cannot See
A proper storm inspection should be methodical. The contractor should assess the roofing system, not just point out the most obvious damaged area. That includes shingles or other roof covering, flashing, vents, pipe boots, valleys, ridges, drip edge, gutters, downspouts, fascia, and visible siding components.
Inside the property, signs such as attic moisture, wet insulation, ceiling stains, peeling paint, or a musty smell may indicate that water has traveled farther than expected. On commercial buildings, drain areas, membrane seams, penetrations, parapet walls, and rooftop equipment curbs also deserve close attention.
Not every storm requires a full roof replacement. A localized repair may be appropriate when the damage is limited, the roof has substantial life remaining, and matching materials are available. Replacement may be the more sensible choice when damage is widespread, the roofing system is near the end of its service life, or repairs would leave the roof with uneven protection and appearance.
That decision should be based on the actual condition of the property, not a one-size-fits-all sales pitch.
How to Prepare for the Adjuster Visit
If possible, schedule your contractor to inspect the property before the adjuster arrives. The contractor can provide photos, measurements, and a written description of observed damage. During the adjuster appointment, having someone familiar with the roof and exterior scope can help ensure that affected components are visible and accurately discussed.
Keep the conversation factual. Share dates, photos, invoices, and observations, but avoid guessing about causes or costs. If the insurer’s initial assessment differs from the contractor’s findings, ask for the differences to be explained in writing. There may be a legitimate reason, or there may be missing information that needs to be reviewed.
It also helps to ask whether code-required upgrades, matching issues, depreciation, supplements, and recoverable depreciation apply to your policy. Coverage varies, and those details can affect the final out-of-pocket cost.
Choosing a Contractor for Storm Claim Restoration
Storms attract out-of-town crews and high-pressure sales tactics. Some contractors do excellent work after major weather events, but property owners should still verify who they are hiring before signing anything.
Look for a contractor with local references, active insurance coverage, clear written estimates, manufacturer certifications, and a documented process for cleanup and communication. Ask who will perform the work, how the property will be protected during construction, and what warranty applies to labor and materials. A professional contractor should be willing to answer direct questions without pressuring you to make an immediate decision.
For larger roofing and exterior projects, make sure the scope addresses the full system. Replacing shingles without correcting damaged flashing, ventilation, gutters, or deteriorated decking can leave weak points behind. The lowest estimate is not always the lowest cost if essential repairs are omitted or the installation is rushed.
CPG Roofing & Siding approaches storm-related work with the same priorities property owners expect after a stressful event: a prompt response, clear documentation, organized scheduling, durable workmanship, and a clean job site when the work is finished.
Restoration Is About Protecting What Comes Next
Once repairs are complete, keep the final invoices, warranty information, photos, and any insurance correspondence in one place. Consider scheduling routine roof and gutter inspections, particularly after severe wind, heavy snow, or repeated freeze-thaw cycles. Maintenance will not prevent every loss, but it can reveal small issues before the next storm tests them.
When weather damages your property, speed matters, but so does judgment. Protect the opening, document the conditions, understand the scope, and choose a contractor who treats your home or building like the long-term investment it is.