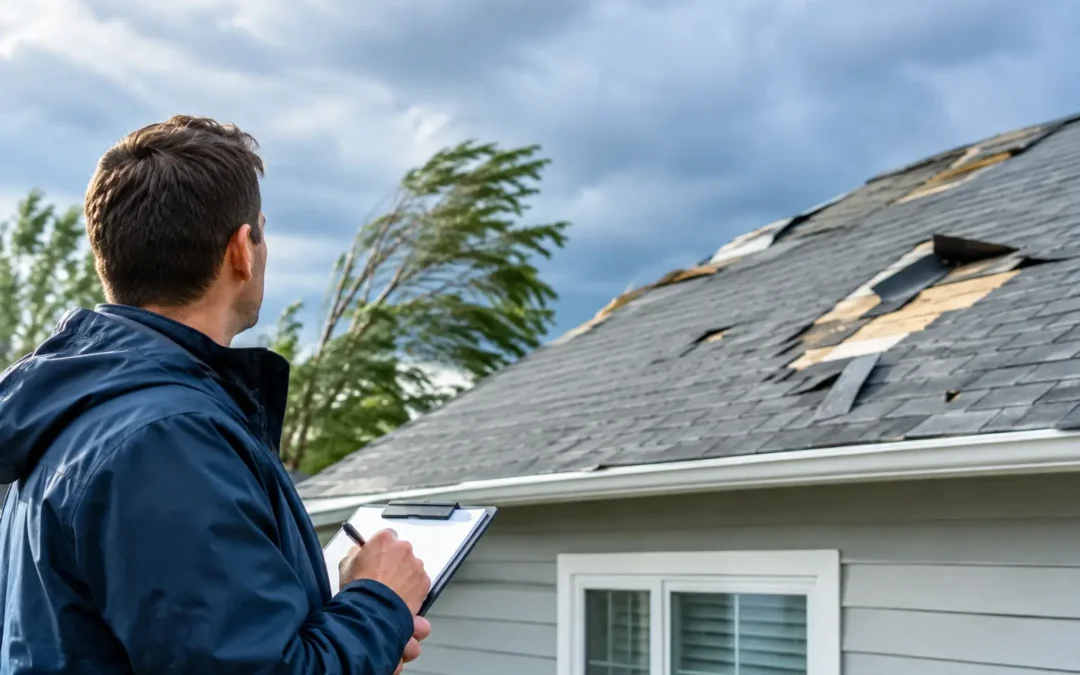
A windstorm can leave your roof looking mostly normal from the driveway while water is already working its way beneath lifted shingles, cracked flashing, or damaged vents. So, does roof insurance cover wind damage? Often, yes – but payment depends on your policy, the cause of the damage, your deductible, and whether the roof was in reasonable condition before the storm.
For homeowners and commercial property owners, the best move is to document the damage quickly, prevent additional water intrusion, and get a professional roof inspection before a small storm issue becomes a major interior repair.
When roof insurance covers wind damage
Most standard homeowners insurance policies cover sudden, accidental wind damage to the roof. If a high-wind event tears off shingles, damages ridge caps, bends flashing, or sends a tree branch through the roof, the dwelling portion of the policy may pay for covered repairs after the deductible.
The word “sudden” matters. Insurance is designed for unexpected events, not for a roof that has slowly worn out over many years. A strong storm that damages a sound roof is very different from ordinary aging, deferred maintenance, or a leak that has existed since last season.
Coverage can also extend beyond the roofing materials. If rain enters through an opening created by wind and damages ceilings, insulation, flooring, or personal belongings, those losses may be covered under other parts of the policy. The insurer will still investigate the source. They may ask whether wind created the opening or whether water entered through an existing maintenance issue.
Commercial policies follow a similar principle, though limits, endorsements, business interruption coverage, and deductibles can be more complex. Property owners should review their policy before storm season rather than trying to interpret it during an emergency.
What insurance may not cover
A wind damage claim is not automatically approved just because shingles are missing after a storm. Insurers typically look at the age and condition of the roof, weather data from the date of loss, maintenance records, photographs, and the adjuster’s inspection findings.
Roof insurance may deny or limit a claim when the damage is tied to poor maintenance, rot, long-term leakage, faulty installation, or normal wear. For example, brittle shingles that fail during a moderate gust may lead to questions about whether the roof was already at the end of its service life.
Cosmetic damage can be another gray area. Wind may scuff shingles, mark metal components, or loosen granules without creating a functional problem. If the roof still sheds water properly and the damage does not reduce its useful life, the carrier may not pay for replacement.
Some policies also contain exclusions or special limits for wind-driven rain when there is no storm-created opening in the roof or walls. Read the policy language carefully. “Wind damage” and “water damage” are related, but they are not always treated as the same claim.
Wind versus flood damage
Wind damage is generally covered under a typical homeowners policy. Flood damage is usually not. If rising water, overflowing waterways, or surface runoff causes damage, a separate flood policy may be needed.
This distinction becomes especially important after severe weather, when a property has both wind-driven rain and water around the foundation. Keep photos and notes that show where and when you first saw the damage. Clear documentation helps establish the cause of loss.
Your deductible can change the decision
Even with coverage, the deductible determines what you pay out of pocket first. If a roof repair costs $2,000 and your deductible is $2,500, filing a claim may not make financial sense. For larger storm losses, the math can be very different.
Some policies use a separate wind or named-storm deductible. It may be a flat dollar amount, or it may be a percentage of the insured value of the home. A percentage deductible can be substantially higher than many owners expect, so check the declarations page rather than assuming your standard deductible applies.
There is also a practical trade-off. Multiple claims can affect future premiums or renewal options, depending on the carrier and your claim history. That does not mean you should avoid a valid major claim. It means you should know the scope of damage, receive a clear estimate, and make an informed decision before filing when circumstances allow.
Actual cash value versus replacement cost
Two policies can cover the same wind event and pay very different amounts. The key difference is often whether your roof is insured for actual cash value or replacement cost value.
Actual cash value coverage factors in depreciation. An older roof may receive a payment based on what it was worth immediately before the loss, not what it costs to install a new roof today. That can leave a sizable gap between the insurance payment and the final replacement bill.
Replacement cost coverage is intended to pay the cost to repair or replace covered damage with comparable materials, subject to policy conditions and limits. Many policies release part of the payment after the work is completed and documented. Do not assume “replacement cost” means every upgrade is covered. If you choose a premium material or a design change beyond the original roof system, you may be responsible for the difference.
If your policy is unclear, ask your agent directly how roof losses are settled, whether depreciation applies, and whether there are age-based limitations for shingles or other roofing materials.
What to do after wind damages your roof
Safety comes first. Stay off the roof, especially after wind, rain, or darkness. Loose shingles, wet decking, fallen limbs, and unstable gutters can make a quick look dangerous.
Start by taking photos and videos from the ground. Capture missing shingles, fallen branches, damaged gutters, water stains, roof debris, and any visible interior leaks. Note the date, approximate time, and storm conditions. If you have pre-storm photos of the property, keep those with the claim file too.
Next, take reasonable steps to prevent further damage. Place containers beneath active drips, move belongings out of wet areas, and arrange for emergency tarping or temporary protection when needed. Most policies require you to mitigate additional loss, but save receipts and avoid permanent repairs until the insurer has had a reasonable opportunity to inspect. Emergency repairs are different from replacing the entire roof.
Then schedule a qualified roof inspection. Wind damage is often difficult to evaluate from the ground. A professional can identify lifted shingles, compromised seals, missing fasteners, cracked pipe boots, displaced flashing, exposed decking, and damage around valleys or roof penetrations. These small failures are where many leaks begin.
If the inspection indicates storm damage, contact your insurer and open a claim. Provide factual details, photos, receipts, and the contractor’s findings. Be accurate without guessing about causes or costs. The adjuster makes the coverage determination, while an experienced roofing contractor can explain the condition of the roof and the work required to restore it properly.
Why a prompt inspection matters in the Hudson Valley
In the Hudson Valley, wind damage can quickly become a bigger problem when it is followed by heavy rain, freeze-thaw cycles, snow, or ice. A lifted shingle may not leak immediately, but repeated weather exposure can allow moisture into the underlayment and roof deck.
Prompt attention also preserves evidence. Loose materials can blow away, emergency patches can obscure the original damage, and interior water stains can spread. An organized inspection report, clear photos, and a written repair scope give you a much stronger record than trying to reconstruct the event weeks later.
For older roofs, an inspection can also clarify whether a focused repair is appropriate or whether storm damage has exposed a broader replacement need. Honest guidance should address both options, including the cost, expected lifespan, and whether the existing roof can be safely repaired without creating new weak points.
Common claim mistakes to avoid
The most damaging mistake is waiting through repeated rainstorms because the roof “doesn’t look that bad.” A delayed response can turn a limited shingle repair into deck, insulation, drywall, and mold-related work.
Avoid signing a contract that promises a new roof before the roof has been inspected and the coverage situation is understood. You should know the scope of work, your deductible, material choices, warranty terms, and your responsibility for non-covered upgrades.
Do not discard damaged materials, invoices, or photos. Keep a simple claim folder with your policy information, inspection report, adjuster correspondence, repair estimates, receipts, and a log of calls. It reduces confusion and helps everyone work from the same facts.
A storm-damaged roof deserves a fast, careful response – not assumptions. If wind has lifted shingles, damaged flashing, or caused a new leak, arrange a professional inspection promptly. CPG Roofing & Siding can help property owners identify damage, secure the roof when needed, and understand the repair work required to protect the building from the next round of weather.